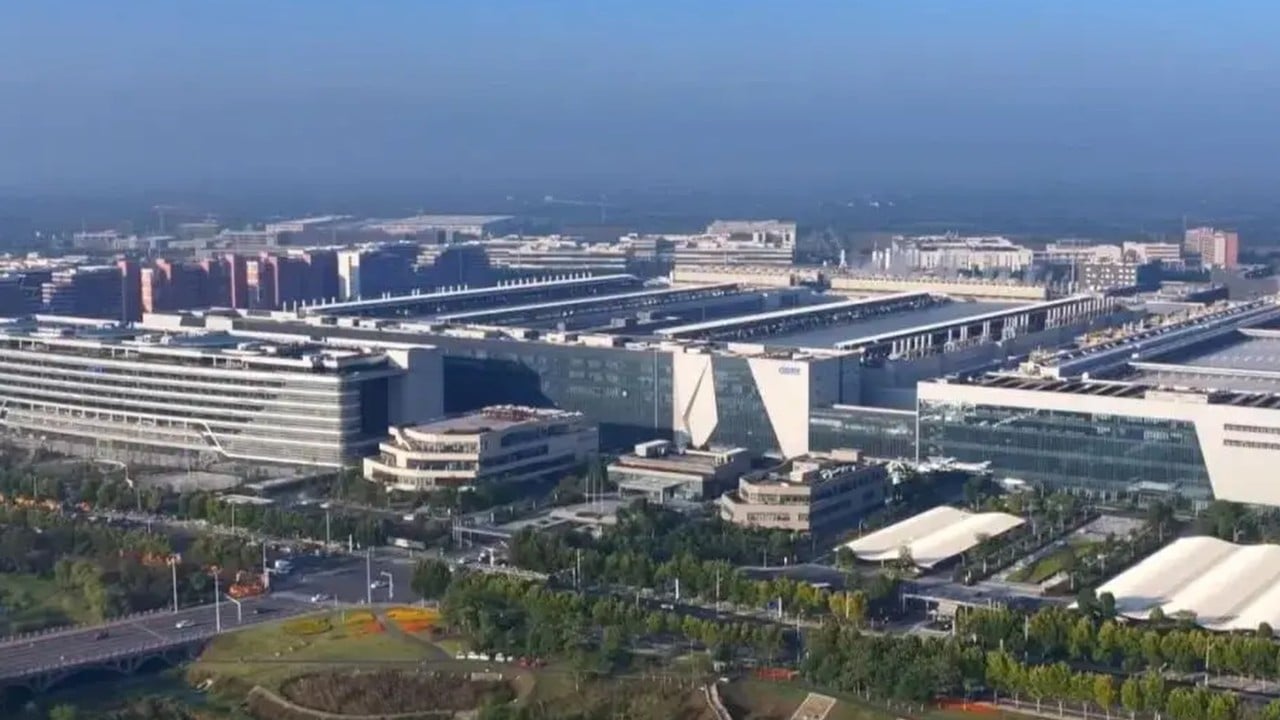
Headline pledges from provincial party leaders rarely alter semiconductor unit economics on their own, yet when Anhui Party Secretary Li Lecheng visited ChangXin Memory Technologies (CXMT) in Hefei three weeks into his tenure and vowed to build integrated circuits into an emerging pillar industry, the visit signaled a tighter alignment between local industrial policy and domestic memory scale.
Standard news coverage treats an official inspection and an expansion vow as proof of inevitable catch-up against incumbent memory suppliers. That framing misses the real mechanics of dynamic random-access memory (DRAM) manufacturing. Memory is a capital-intensive, yield-sensitive, and depreciation-heavy business where scale only compounds value when wafer capacity, lithography tool access, cell architecture, and end-market qualification clear bottlenecks simultaneously.
A rigorous reading of the Hefei development requires separating observed facts from educated hypotheses, then examining how capital, technology, and geopolitical friction interact inside a single fab network.
Known Facts Versus Educated Hypotheses
Separating confirmed developments from analytical inference prevents overreading political rhetoric.
Known facts establish the baseline of CXMT's position and policy backing:
- Li Lecheng, former Minister of Industry and Information Technology and newly appointed Anhui provincial party secretary, conducted an on-site inspection at CXMT in Hefei and pledged provincial support for the integrated circuit sector.
- CXMT reported progress on a 4F2 memory cell architecture and targeted a server memory product rollout by the end of 2026, alongside fifth-generation process mass production and LPDDR5X showcases.
- Global memory supply-demand tightness has lifted industry pricing and revenue in 2026, while domestic Chinese equipment suppliers have raised localization shares in Chinese fabs.
Educated hypotheses extend those facts into forward-looking operational claims:
- Provincial backing in Anhui likely accelerates land allocation, utility infrastructure, grid stability, and municipal co-investment faster than cleanroom equipment delivery timelines.
- Moving from consumer/mobile DRAM into enterprise server memory and denser cell layouts will test CXMT's yield curves and reliability qualification cycles before volume revenue scales materially outside captive channels.
- Even if domestic memory supply expands rapidly, export controls and customer qualification hurdles will keep global market share constrained relative to raw wafer capacity growth.
The Four Structural Pillars of CXMT Expansion
Evaluating whether CXMT can convert political backing into durable competitive advantage works best through four operational pillars: Capacity Scaling, Architecture and Node Progression, Equipment and Yield Economics, and Market Qualification.
Capacity Scaling and the Capex Treadmill
DRAM is a classic fixed-cost game governed by learning curves and wafer starts per month (WSPM). Once a cleanroom shell is built, profitability depends on keeping expensive tools running near full utilization while absorbing steep depreciation.
Two distinct mechanisms drive capacity expansion in a Hefei-anchored model:
- Brownfield and greenfield line additions: Adding new fab modules or expanding monthly wafer throughput increases fixed-cost absorption per gigabit produced, provided cleanroom utilities, chemical supply, and test capacity scale in lockstep.
- Product-mix capacity consumption: Transitioning toward higher-density nodes or server-grade parts often consumes more process steps per wafer, which can cap effective bit output even when nominal wafer starts rise.
The primary limitation here is timing asymmetry. Municipal governments can approve permits and mobilize local capital rapidly, whereas specialized deposition, etch, metrology, and lithography tools carry long lead times and strict installation tolerances.
Architecture and Node Progression
Reporting progress on a 4F2 architecture and targeting server memory by late 2026 points to an effort to push density and enter higher-value tiers. In DRAM design, shrinking cell footprint and improving capacitor aspect ratios are essential to lower cost per bit and meet power-efficiency targets.
Server memory imposes stricter requirements than standard consumer DRAM. Data center customers demand tight signal integrity, low error rates under sustained thermal loads, long validation cycles with server platform vendors, and consistent supply across multi-quarter procurement windows. Advancing cell architecture helps on density, yet reliability validation and high-volume yield maturity determine whether a design wins socket share in enterprise racks.
Consider a hypothetical server validation cycle: even if a memory vendor samples qualified dies on schedule, large cloud and enterprise buyers typically run multi-stage burn-in, compatibility, and endurance testing before committing primary volume. Any gap in yield uniformity or thermal consistency pushes full commercial ramp into subsequent quarters.
Equipment and Yield Economics
A provincial pledge cannot bypass the physics of patterning sub-micron structures or the economics of fab yield. Semiconductor manufacturing operates on a brutal cost function: total fab cost divided by good dies per wafer determines unit economics.
When advanced lithography tools face export restrictions, fabs must rely on available deep ultraviolet (DUV) systems, multiple patterning techniques, or domestic alternatives where qualified. Every extra patterning step introduces overlay error risk, longer cycle times, and higher defect density.
The second limitation involves tool maturity across the entire process flow. Reaching 35% domestic equipment adoption in Chinese chipmaking represents meaningful progress in select sub-systems, yet memory manufacturing requires tight coordination across etch, deposition, inspection, and lithography. A single bottleneck step with lower throughput or higher particle counts can pull down overall line yield and raise scrap costs.
Market Qualification and Demand Absorption
Memory demand in 2026 has benefited from tight supply and strong AI and server memory pull, creating a favorable pricing window for suppliers with available inventory. Still, shipping volume inside China differs sharply from winning global enterprise accounts.
Domestic demand provides an immediate absorption buffer. Chinese OEMs, module makers, and system integrators face strong incentives to dual-source or localize standard DRAM when supply is tight or trade friction rises.
Global expansion faces harder headwinds. Non-Chinese hyperscalers and tier-one OEMs weigh geopolitical compliance risk, export-control exposure, and long-term supply continuity alongside price and performance. A provincial party chief can champion domestic and overseas expansion, but commercial procurement teams in foreign supply chains price in regulatory tail risk before shifting core allocations.
Cause-and-Effect Chains Standard Coverage Misses
Surface-level reporting often treats policy support as a direct cause of market share gains. In practice, intermediate causal links govern the outcome:
- Provincial support lowers local friction, not global trade friction. Stronger Hefei coordination can speed up permitting, power hookups, and local financing, which helps domestic execution, but it does not remove external export controls or foreign buyer scrutiny.
- Tight global DRAM pricing improves cash flow today, while raising cycle risk tomorrow. Elevated prices and strong revenue growth generate capital for expansion, yet memory markets historically swing from shortage to oversupply when multiple suppliers add capacity simultaneously.
- Chasing server and denser nodes improves margin potential, but slows early yield ramp. Higher-value memory tiers offer better economics if yields stabilize, but tighter specifications increase engineering and qualification overhead during initial production.
Tactical Execution Logic for Decision-Makers
Trackers evaluating CXMT, competing memory suppliers, or affected hardware supply chains should monitor concrete operational signals rather than diplomatic headlines:
- Audit cleanroom-to-tool milestones. Compare announced wafer capacity goals against actual tool deliveries, cleanroom readiness, and ramp schedules rather than treating policy pledges as installed capacity.
- Separate sample announcements from volume qualification. Treat a late-2026 server memory target as an engineering milestone until independent system validations and recurring commercial orders confirm production scale.
- Benchmark yield and cost-per-bit trajectories. Watch for clues on process steps, die size, and defect rates, because high wafer starts with mediocre yield still produce high cost per gigabit.
- Segment domestic vs. export demand. Model domestic Chinese absorption separately from international OEM qualification, recognizing that regulatory constraints can bifurcate supply chains.
- Stress-test against the next memory cycle. Avoid assuming peak-cycle pricing and shortages are permanent; evaluate how cost structures hold up when industry supply catches up with demand.
No single policy initiative or fab expansion plan is a silver bullet in memory manufacturing. High capital intensity, steep learning curves, export restrictions, and cyclical pricing remain real constraints that can compress margins even when output rises.
For hardware buyers, investors, and strategists, the highest-leverage move is to treat CXMT's Anhui backing as a catalyst for faster domestic supply localization and mid-tier DRAM competition, while hedging global procurement and portfolio plans against cross-border regulatory bottlenecks and the next cyclical turn in memory pricing.