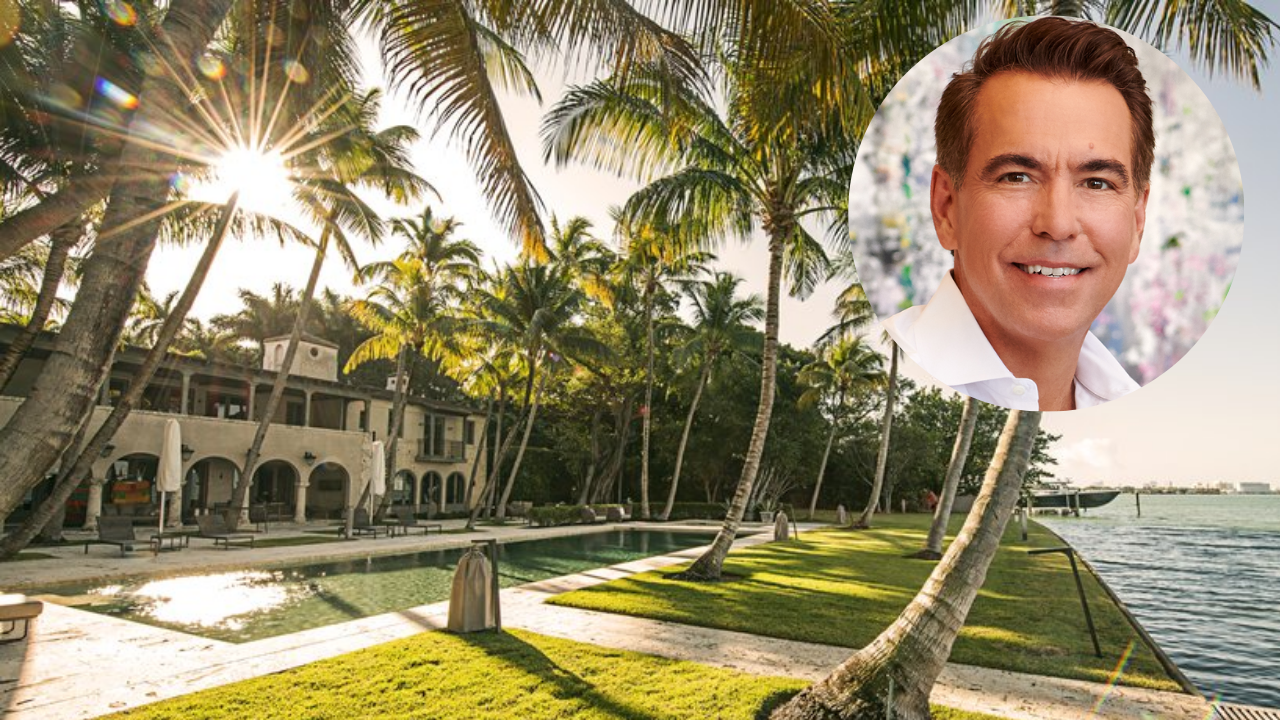
Ultra-prime real estate transactions at the nine-figure and upper eight-figure threshold are rarely driven by traditional domestic housing utility. When technology billionaire Orlando Bravo acquired Phil Collins’s historic 1929 Miami Beach estate for 39.25 million dollars, the transaction functioned as an exercise in capital preservation, historical arbitrage, and portfolio asset restructuring rather than a conventional residential purchase. Deconstructing transactions of this magnitude requires moving past the celebrity provenance and examining the underlying economic mechanisms: land value concentration, historical preservation incentives, systemic liquidity constraints in trophy asset classes, and the risk-adjusted return profiles of physical storehouses of wealth against volatile
The Economics of Ultra Luxury Real Estate Asset Allocation
business, lifestyle Also making waves lately: Why Separating Your Work and Personal Life is Career Suicide.
Ultra-prime residential real estate transactions are rarely governed by standard market mechanics. When billionaire tech investor Orlando Bravo acquired Phil Collins's historic 1929 Miami Beach estate for $39.25 million, the purchase was frequently mischaracterized through the lens of traditional consumer home-buying behavior. In elite asset classes, a residential acquisition functions as a specialized capital preservation vehicle, an illiquidity play, and an exercise in risk mitigation within a diversified macro portfolio. Understanding the true mechanics of this transaction requires deconstructing the cost functions, spatial scarcity factors, and structural liquidity constraints that define the ultra-luxury property tier.
The Valuation Mechanics of Historic Coastal Assets
Evaluating a property built in 1929 within a prime coastal geography like Biscayne Bay involves reconciling conflicting valuation drivers. Standard square-footage metrics collapse when applied to architecturally significant, waterfront land parcels. The total acquisition cost is a composite of three primary variables: underlying land scarcity, historical preservation premiums, and structural modification liabilities. More information into this topic are explored by CNBC.
Waterfront land in Miami Beach represents a finite physical supply curve. Unlike suburban expansions or commercial multi-family developments, coastal frontage cannot be manufactured. The capital allocation strategy behind a thirty-nine-million-dollar purchase price relies on the inelasticity of this supply. When an investor acquires an estate associated with cultural provenance, such as the former residence of a major recording artist, the pricing structure incorporates an intangible asset premium. However, this intangible value is offset by an immediate operational liability: aging infrastructure.
A 1929 construction date implies structural obsolescence regarding modern electrical grids, foundation load tolerances, sea-level resilience, and HVAC efficiency. Consequently, the initial purchase price is merely the entry cost. The total capital expenditure function includes a mandatory, highly specialized rehabilitation phase. The economic rationale relies on the assumption that post-renovation market value will outpace the cumulative sum of acquisition costs, regulatory holding expenses, and construction capital injections.
Capital Preservation versus Yield Generation
Standard residential real estate is evaluated based on capitalization rates, rental yield, and cash-flow generation. In the ultra-prime segment, these metrics are largely irrelevant. Assets priced in the tens of millions are typically acquired with substantial equity or entirely unencumbered by traditional mortgage debt, neutralizing interest rate sensitivity in the short term.
Instead of yield, the governing principle is capital preservation and wealth defense against inflationary pressures. High-net-worth allocators treat prime real estate as a non-correlated asset class designed to hedge against currency depreciation and equity market volatility. Real assets situated in globally recognized cultural and financial hubs act as a sovereign risk hedge. If domestic tax regimes, regulatory frameworks, or currency values fluctuate, physical property provides a tangible store of value that can be collateralized or liquidated, albeit with significant friction.
The liquidity profile of a $40 million asset is fundamentally different from that of a standard single-family home. The buyer pool is globally restricted to a microscopic percentage of the population. This creates extreme price volatility at the margin and long holding periods. An investor entering this tier must possess the balance sheet capacity to absorb prolonged illiquidity without facing forced divestment pressures.
Regulatory and Environmental Risk Factors
Executing a high-capital real estate transaction in coastal Florida requires navigating complex structural risk variables that do not apply inland. Climate vulnerability and municipal zoning regulations dictate long-term asset performance.
Coastal properties face escalating insurance costs, stricter building codes, and physical risks associated with sea-level rise and extreme weather events. The total cost of ownership includes catastrophic risk mitigation, which can significantly alter the annual operational yield of the property. Insurance premiums for waterfront mansions have experienced exponential growth, shifting the ongoing holding cost structure. Furthermore, historic preservation designations often impose severe restrictions on architectural modifications, creating friction between modern luxury requirements and historical preservation mandates.
Investors must factor municipal approval timelines and environmental compliance costs into their initial underwriting model. A failure to accurately project these regulatory frictions can transform an appreciation play into a capital sinkhole.
Portfolio Integration and Strategic Exit Dynamics
For an investor whose primary wealth is generated in private equity or technology, a trophy real estate asset serves a distinct portfolio function. It is a non-liquid liquidity buffer and a generational wealth transfer mechanism.
The exit strategy in the ultra-luxury tier is rarely time-sensitive. Sellers operate with immense optionality, capable of holding an asset for decades until a macroeconomic expansion cycle aligns with a qualified buyer pool. The underlying thesis of acquiring a Miami Beach estate at this valuation point is anchored in the long-term migration of global wealth toward Tier-1 tax-favorable urban centers with coastal access. As global capital concentrates in specific geographic nodes, the terminal value of finite waterfront parcels is projected to appreciate irrespective of broader regional economic contractions.
Allocate capital to ultra-prime coastal assets exclusively when the investment horizon exceeds ten years, the holding costs are insulated from cash-flow dependencies, and the acquisition functions as an unhedged long position on structural geographic scarcity.